Presented by RGA
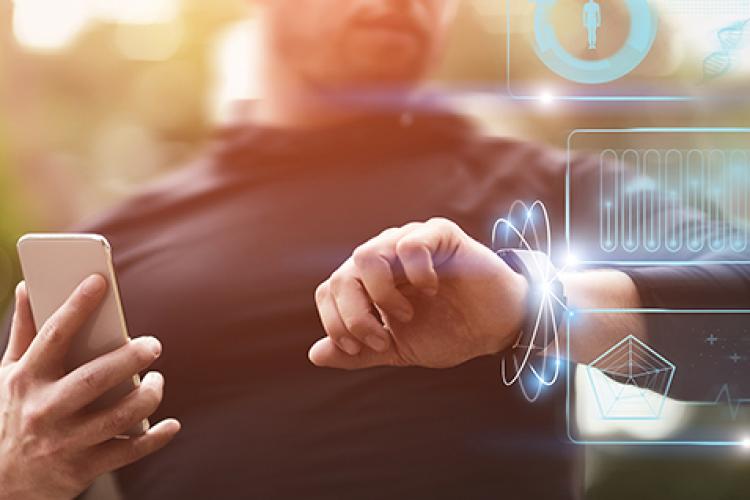
An RGA analysis of medical expenses indicates that lifestyle data from wearable devices can indeed help health insurers better assess risk, improve underwriting, and develop propositions that incentivize healthy lifestyles.
Presented by RGA
An RGA analysis of medical expenses indicates that lifestyle data from wearable devices can indeed help health insurers better assess risk, improve underwriting, and develop propositions that incentivize healthy lifestyles.
Sustainability should be understood and applied more broadly in the context of life and health insurance. In her latest blog article, Daisy Ning, Head of Life & Health Reinsurance APAC ex. China at Swiss Re, explains why sustainability should directly align with the 3As of insurance.
Click here to read Michel Léonard's bio >
View More Articles Like This >
Inflation and Insurance Replacement Costs: Key insights into the relationship between inflation and insurance replacement costs as basis for P&C / Non-Life capital allocation line performance, and solvency
Presented by Oliver Wyman
As the insurance industry is starting to evolve, the small and medium business (SMB) market becomes an interesting growth opportunity. Digital capabilities and data become more available and prolific, and customer needs and wants are beginning to shift, opening new value pools.
Oluremi Owolabi Fadi, Team Lead, Oil&Gas and Financial Institutions, Custodian Life Assurance Limited
Steve Cramer, Senior Vice President & Chief Product Officer, Retirement Division, Protective Life Insurance Company
Joseph Strathman, Director, Business Transformation, Transamerica Life Insurance Company
Life insurance customers are increasingly segmented by gender, race, ethnicity, and other characteristics. Many of these groups are underserved and with unique needs, creating challenges for insurance carriers to reach them.
Presented by Milliman
As many firms expand beyond traditional allocations to fixed income and mortgage-backed securities, this report provides a guide to 11 alternative asset classes insurers may wish to consider.
We are continuing to face a very uncertain environment — war in Europe, higher inflation, the lingering effects of the pandemic, increased likelihood of recession, questions on the right direction and speed of movement on climate/ESG, evolving market pricing cycles, and moderating rates. Oliver Wyman shares 10 actions CEOs should take to Reinvent Insurance and fuel growth in 2023.